Is YouTube a Hobby or a Business? How the IRS Decides
YouTube hobby or business for the IRS: the nine factors with creator evidence, the dollar difference on $8,000 of income, and when Form 5213 backfires.
If your channel earns ad revenue or sponsor money but spends more than it brings in, you have probably wondered whether the IRS sees a YouTube channel as a hobby or a business. The answer is decided by facts about how you run the channel, not by what you call it, and the label is worth thousands of dollars in a loss year. This guide gives you the nine factors the IRS uses, translated into evidence a creator can actually keep, the tax difference computed on $8,000 of channel income, and the honest case for and against Form 5213.
This is general information, not tax advice, and Paschal is not licensed to give it. The primary sources are the regulation itself and the IRS hobby or business fact sheet; bring your own numbers to a tax professional before you file. The rest of the creator tax guide, every form, tax and calculator in filing order, is at Creator Taxes.
The short answer: profit motive, proven by facts
The tax code calls a hobby an “activity not engaged in for profit,” meaning anything whose costs don’t qualify as trade-or-business or investment expenses. The regulation adds two details that matter more than any checklist. You don’t need a reasonable expectation of profit, only a genuine objective of making one. And the IRS gives more weight to objective facts than to your statement of intent.
So saying “it’s a business” on Schedule C proves nothing. Neither does a 1099 from AdSense or a brand, which only shows you were paid. Forming an LLC doesn’t settle it either; by default a single-member LLC owned by an individual still reports on Schedule C, as covered in whether a YouTube channel needs an LLC.
I ran a YouTube channel by myself past 130,000 subscribers. What that looked like day to day was a production schedule: shooting, cutting in Final Cut, uploading, checking what worked, changing the next video. That routine is exactly what the IRS factors are trying to detect. The work itself is the evidence, if you write it down.
What the label changes on your return
A business reports on Schedule C. A hobby’s income goes on Schedule 1, line 8j, “Activity not engaged in for profit income”. The differences after that are large.
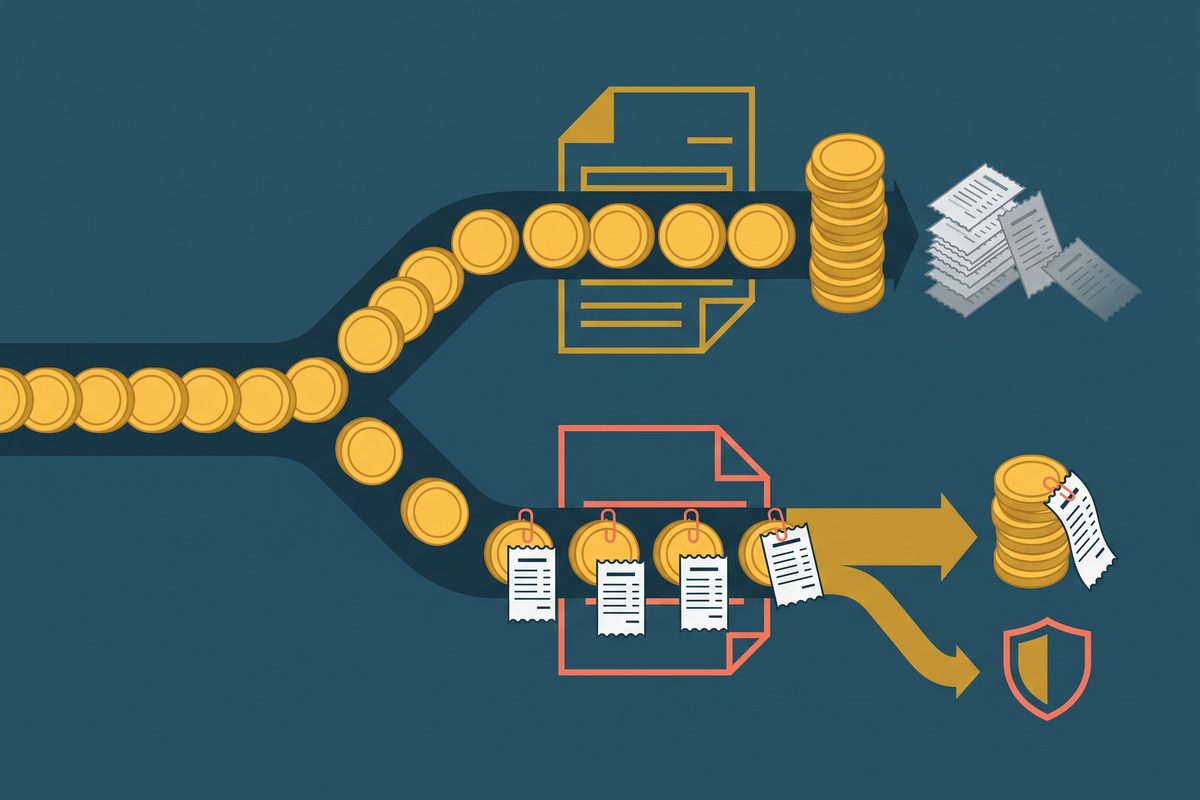
Hobby expenses are miscellaneous itemized deductions, and those have been disallowed for every tax year beginning after December 31, 2017. Several pages still say the deduction could return after 2025. It won’t: Public Law 119-21 struck the “before January 1, 2026” end date, so the disallowance is now permanent. A hobby loss also can’t offset your salary or any other income.
The one thing a hobby avoids is self-employment tax, because that tax only reaches net earnings from a trade or business. A business pays 15.3% on 92.35% of net profit once that figure reaches $400, then deducts half of it and may take the 20% qualified business income deduction, figured on profit reduced by that half.
To put dollars on it, here is a script-computed comparison (calculated October 5, 2026). Assumptions: tax year 2026, single filer whose day job already puts them in the 22% bracket, which runs from $50,400 to $105,700 of taxable income; $8,000 of channel income; three expense levels; state tax ignored.
| Channel expenses | Hobby: federal tax added | Business: SE tax | Business: QBI deduction | Business: income tax change | Business: total | Hobby costs more by |
|---|---|---|---|---|---|---|
| $10,000 (loss year) | $1,760 | $0 | $0 | -$440 | -$440 | $2,200 |
| $5,000 | $1,760 | $424 | $558 | $491 | $915 | $845 |
| $0 | $1,760 | $1,130 | $1,487 | $1,309 | $2,439 | -$679 |
The loss year is where the label matters most. As a business, the $2,000 Schedule C loss cuts tax on the day-job salary by $440. As a hobby, all $8,000 is taxed and the $10,000 of spending disappears, a $2,200 swing on one year. A business loss also leaves no QBI deduction that year; the negative QBI carries forward and reduces next year’s deduction.
The last row is the one nobody mentions. A channel with almost no expenses would pay $679 less as a hobby, because it skips self-employment tax. That is not a choice you get to make. If the facts show a profit motive, it’s a business, and that self-employment tax is your Social Security and Medicare contribution, not a penalty. To see how that tax works line by line, read self-employment tax explained or run your own number in the self-employment tax calculator. What counts as a deductible expense in the first place is covered in creator tax deductions.
The nine factors, translated for a channel
No single factor decides the question, and the regulation says you can enjoy the work and still be in it for profit. The list below follows the order in Treasury Regulation 1.183-2(b). The right-hand column is what to keep, because an examiner looks at records, not intentions.
Creator evidence checklist:
| Factor (Reg. 1.183-2(b)) | What it looks like for a channel | Evidence to keep |
|---|---|---|
| 1. Manner of carrying on the activity | Separate money, books kept as you go, changes when something stops paying | Business bank account, monthly income and expense ledger, notes on what you changed and why |
| 2. Expertise of you or your advisors | You studied how channels earn and followed it, or asked people who know | Course receipts, notes from creator programs, sponsorship rate research, emails with your tax preparer |
| 3. Time and effort | Regular hours, especially on work that isn’t fun | Upload calendar, time log split by scripting, filming, editing and admin |
| 4. Expected appreciation of assets | The regulation’s example is land; for a channel, a back catalog that keeps earning is the closest match, and it rarely carries much weight | Evergreen video list, back-catalog revenue by year, licensing inquiries |
| 5. Success in similar activities | You’ve made something like this profitable before | Records from a prior channel, blog, app or product that turned a profit |
| 6. History of income or losses | Losses limited to a startup period, or explained by events outside your control | Year-by-year profit and loss, notes on demonetization, policy changes or equipment theft |
| 7. Amount of occasional profits | A big year now and then, or a real chance of one | Sponsorship pipeline, signed deals, revenue spikes tied to specific videos |
| 8. Your financial status | Whether the losses mainly serve to shelter other income | Nothing to file; just know that a high salary plus recurring channel losses draws attention |
| 9. Personal pleasure or recreation | Enjoyment is fine if the rest of the file shows profit-seeking | Content plan aimed at revenue, not only at what you like making |
Factor 3 is where solo creators are strongest and keep the least proof. When I was handling every step alone, the hours went into filming, editing and uploads, week after week. A plain spreadsheet with dates and hours would turn that into evidence. Factor 1 is where small channels are often weakest. If personal and channel money share one account, fix that first; it is the cheapest factor to win.
The 3-of-5 presumption, and what it doesn’t do
If an activity shows a profit in at least 3 of 5 consecutive tax years, ending with the year in question, the law presumes it is engaged in for profit. A profit year here means gross income from the activity exceeded its deductions. Horse activities use 2 of 7 years instead.
The presumption is a starting point, not a pass. It shifts who has to prove what, and it leaves the nine factors in play. Missing it is not fatal either. The regulation says losses during the startup period that an operation customarily needs don’t by themselves show a lack of profit motive.
One plan shows up in creator forums: skip some real expenses to report a $1 profit and tick the box. That is a bad trade. You pay tax on income you could have offset, and the IRS audit guide tells examiners to watch for income or expenses manipulated for the sole purpose of meeting the presumption. A thin profit manufactured by leaving deductions off does nothing for the nine factors either.
Form 5213: postponing the question
Form 5213 asks the IRS to hold off deciding whether the presumption applies until the end of the fifth tax year of the activity. The deadline is 3 years after the due date (without extensions) of the return for the first year you engaged in the activity. If the IRS sends written notice proposing to disallow your deductions before then, you have 60 days from the notice, and that window does not stretch the 3-year limit. It goes to the IRS service center on its own, not attached to your return.
The price is time. Filing automatically extends the period the IRS has to assess tax on that activity, for every year in the five-year window, until 2 years after the due date of the return for the last year in that window.
When not to file Form 5213
Four situations where the form works against you:
- You’re profitable from the start. If the channel makes money in its first years, there are no losses for the election to protect, and you’ve only kept those years open longer.
- Nobody has asked yet. Inside the 3-year window, the 60-day rule lets you wait and file only if the IRS actually questions the activity. Filing early hands the IRS a longer clock for no benefit today.
- You don’t expect three profit years in the first five. The election only postpones the presumption test; if you won’t pass it, you’ve extended the assessment period and gained nothing.
- The channel isn’t in its first years. The election is tied to when you first engaged in the activity, so a channel that has been running for a while is usually past the window.
The audit guide also warns examiners that only a valid, complete and timely election extends the statute, which tells you the IRS reads these forms closely. File one only after a tax professional has looked at your first-year numbers.
Channel plus an app or ebook: one activity or two?
A channel often runs next to a course, an ebook or an app. Under the regulation, separate activities are judged separately, so a profitable product doesn’t automatically rescue a losing channel. Whether two undertakings count as one depends on how closely they are tied together economically and organizationally, the business purpose for running them together, and how similar they are.
The IRS generally accepts how you characterize your activities, unless the grouping is artificial and can’t be reasonably supported. If the channel’s main job is selling your ebook, with the funnel and the numbers to show it, treating them as one activity is defensible. If they’re unrelated, don’t lump them together to hide a loss.
The IRS no longer publishes Pub. 535, its old business expense guide; its small-business coverage now sits in Publication 334, which includes a section on activities not engaged in for profit.
Keep the file, not the label
The return only asks you to pick a form. The classification is won or lost on records you build during the year, and for most channels the three that matter are a separate account, an hours log, and a dated note each time you change strategy because something wasn’t paying. For the rest of the filing picture, from Schedule C to estimated payments, see how creators pay taxes.
Open a folder this week named for the tax year, put your last 12 months of channel income and expenses in it, and start the hours log today.
Frequently asked questions
Does getting a 1099 make my YouTube channel a business?
No. A 1099 reports that you were paid; it says nothing about profit motive. The IRS decides hobby versus business from the facts of how you run the channel, using the nine factors in Treasury Regulation 1.183-2(b). Hobby or business, the income still has to be reported.
Can I deduct hobby expenses up to my hobby income?
Not anymore. Hobby expenses are miscellaneous itemized deductions, which were suspended starting in 2018. The 2025 tax law (Public Law 119-21) removed the end date, so the suspension is now permanent. A hobby creator pays income tax on gross hobby income with no offset.
Do hobby creators pay self-employment tax?
No. Self-employment tax applies to net earnings from a trade or business, and a hobby is not one. Hobby income goes on Schedule 1, line 8j, and is subject to income tax only. That is rarely a good trade, because the expenses are lost too.
Does forming an LLC make my channel a business for the IRS?
No. By default a single-member LLC is disregarded for income tax and an individual owner still files Schedule C. The hobby rules look at how the activity is run, not the legal wrapper. An LLC with no records, no plan and years of losses is still exposed. The entity can help with liability, not with classification.
Sources
- 26 CFR 1.183-2: Activity not engaged in for profit defined (eCFR)
- 26 U.S. Code § 183: Activities not engaged in for profit (Cornell LII)
- 26 U.S. Code § 67: 2-percent floor on miscellaneous itemized deductions (Cornell LII)
- IRS FS-2022-38: Know the difference between a hobby and a business
- IRS Form 5213: Election to Postpone Determination as To Whether the Presumption Applies
- IRS: Activities Not Engaged in for Profit Audit Technique Guide (Pub 5558)
- IRS: 2025 Schedule 1 (Form 1040)
- IRS: Instructions for Schedule SE (Form 1040)
- IRS: Instructions for Form 8995
- 26 U.S. Code § 1402: Definitions (Cornell LII)
- IRS: Tax inflation adjustments for tax year 2026
- IRS: Self-employment tax (Social Security and Medicare taxes)
- IRS Publication 334 (2025): Tax Guide for Small Business
- IRS: Single member limited liability companies
This article is general information based on the author's experience. It is not licensed financial, legal, or tax advice. See the editorial policy.