Tax Deductions for Content Creators: The Line-by-Line Map
Every creator deduction mapped to its Schedule C line, the IRS publication behind it, and the limit that bites — plus four deductions that never touch Schedule C.
An AdSense payout lands gross, the tax on it is already owed, and expenses are the only number on the return you still control. This article maps each category a creator spends in to its Schedule C line, the IRS publication behind it, and the limit or election that changes the result. It then covers the four deductions that are not on Schedule C at all, where first-year creators most often get the math wrong. The seven-row short version is in how creators pay taxes; this is the long one.
Paschal is not licensed to give tax advice; this is general information for US creators, not advice for your return. Primary sources are the IRS Schedule C instructions and Publication 334; publications cited are the 2025 editions, the latest issued as of September 2026, with 2026 figures from IRS news releases. For your own numbers, talk to a tax professional.
The test every expense has to pass
Schedule C uses one standard: the expense has to be ordinary and necessary for the business. Ordinary means common in your kind of business; necessary means helpful and appropriate, not indispensable. A capture card is ordinary for a streamer. A second monitor is necessary for an editor. A standing desk is both, and the IRS does not argue about any of them.
Two qualifiers sit on top of that standard. Anything shared with personal life counts only for its business share, so a phone that is 60% channel gets 60% of its bill. And if the activity is a hobby rather than a business, the income is still reportable but the expenses are not deductible at all. The IRS decides hobby-or-business on eight factors, the first of which is whether you keep complete and accurate books. Records are not paperwork after the fact; they are the evidence that the deductions exist.
The working rule I use on my own channel: if I cannot say which video or which product a purchase served, it does not go on the form.
Gear: cameras, computers, phones
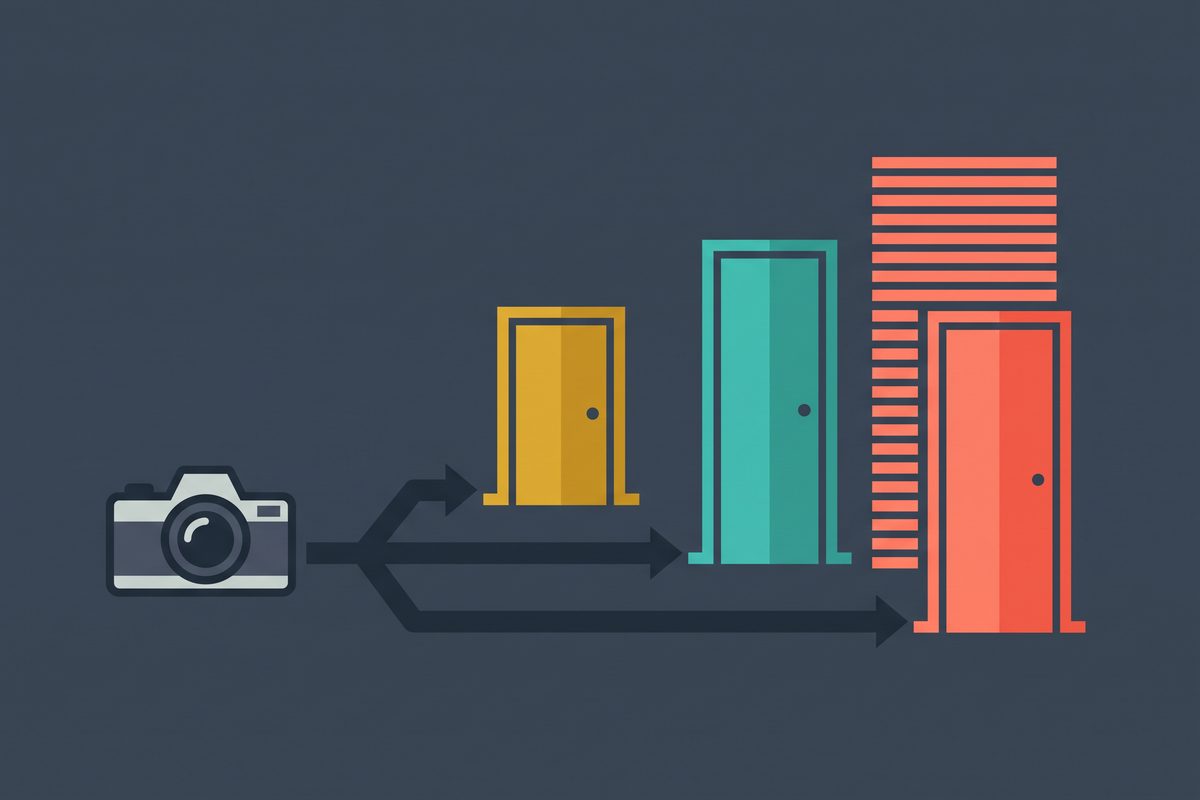
Equipment is the category every creator has and the one most guides describe backwards. The default is depreciation over years, but three doors let you take the cost sooner, and for a one-person channel the first door handles almost everything.
Gear, mapped:
| Item | Schedule C line | Governing source | The election or limit | Keep |
|---|---|---|---|---|
| Any item or invoice up to $2,500 (mic, lens, light, monitor, drive) | Line 22 (supplies) or 27a (other), expensed in the year paid | De minimis safe harbor, Reg. 1.263(a)-1(f) | $2,500 per invoice or per item for taxpayers without an audited financial statement; a statement titled “Section 1.263(a)-1(f) de minimis safe harbor election” attached to the timely filed return each year | The invoice showing each item’s price separately |
| Camera body, computer, or rig over $2,500 | Line 13 (depreciation and Section 179) via Form 4562 | Publication 946 | Section 179 limit $2,500,000 for tax years beginning in 2025; 100% bonus depreciation for property acquired after January 19, 2025; business use must exceed 50% to take the full first-year write-off | Purchase date, price, placed-in-service date, business-use estimate |
| Phone and its bill | Line 27a (device at business share) and line 25 or 27a (service) | Publication 334 | Business-use percentage only; a dedicated business line is 100% | A month of usage or call logs that supports the percentage |
| Free product received for a review | Income first (Part I), then treated like a purchase at its value | Gig economy tax center | Income must be reported whether paid in cash, property, goods, or virtual currency | The brand’s email stating retail value, and proof the item is used on the channel |
The de minimis line is the one to read twice. A $1,900 camera body plus a $400 microphone plus a $600 light are three items, each under $2,500. All three are expensed in the year of purchase with no depreciation table, as long as the election statement goes in with the return. Without the statement, the safe harbor does not apply to that year. Buy a $3,200 cinema camera and you are in Publication 946, where Section 179 and 100% bonus depreciation still give you the full deduction in year one, with Form 4562 and a business-use percentage attached.
Phones are softer than cars. The car rules in Publication 463 demand a contemporaneous log; the phone rule is a reasonable business-use allocation you can defend. Pick a percentage from a real month, write down how you got it, then use that number all year.
Software, fees, plus the money that never reached you
Subscriptions are current expenses with no election to worry about. The trap in this category is the fee that was deducted before the money hit your account.
| Item | Schedule C line | Governing source | The rule that bites |
|---|---|---|---|
| Editing, design, scheduling, stock music, cloud storage subscriptions | Line 18 (office expense) or 27a | Publication 334 | Business-use share if the same account edits family videos |
| Platform and payment-processing fees (Patreon, PayPal, Stripe, marketplace cuts) | Line 10 (commissions and fees) | Schedule C instructions | Deduct the fee only if you reported the gross; if your books already show the net payout, the fee is already gone |
| Business bank and card fees | Line 27a | Publication 334 | Business account only |
| Equipment and liability insurance | Line 15 (insurance other than health) | Schedule C instructions | Health premiums do not go here; see the last table |
| Website hosting, domain, email platform | Line 18 or 27a | Publication 334 | Current expense; no depreciation for a hosting bill |
The gross-versus-net point is where two of the top ten guides go wrong by omission. A platform that keeps $100 of a $1,000 pledge and sends you $900 has already reduced your income; report $1,000 and deduct $100, or report $900 and deduct nothing, never $900 and $100. I spent time in finance before going independent, and the reflex that stuck is reporting gross on every stream and taking the fee as a visible line. It makes the payout report and the return reconcile to the dollar.
The room you film or edit in
The home office deduction is worth taking and easy to lose. Publication 587 has two tests and two methods.
| Question | Answer from Publication 587 | What it means for a creator |
|---|---|---|
| Which space qualifies? | A specific area used only for the business (exclusive use) and used regularly, not occasionally | A spare room with the set in it qualifies; the couch you also watch TV from does not, even with a ring light next to it |
| Does it have to be my main place of work? | Yes, or it must be where you do administrative and management work with no other fixed location for it | Editing and answering sponsors from that room satisfies this even if you film elsewhere |
| Simplified method | $5 per square foot, 300 square feet maximum, so $1,500 at most; no depreciation; no carryover of unused expenses | Fast, and it avoids the depreciation recapture bookkeeping a homeowner otherwise inherits |
| Actual method | Form 8829: direct expenses in full, indirect expenses (rent, utilities, insurance) at the business percentage, plus depreciation for owners | Usually larger for a renter with one dedicated room in an expensive city |
| Can I switch? | The choice is per year and irrevocable once the return is filed | Run both numbers before filing, not after |
Position: a renter with a real dedicated room should run Form 8829, because rent at a 15% business share passes $1,500 once annual rent passes $10,000, which is arithmetic, not opinion. A homeowner with a small office should take the simplified method and skip the depreciation question entirely. Either way, measure the space once, photograph it, then file the number on line 30.
Driving, travel, meals — and the entertainment trap
Publication 463 governs this whole category and it is the one publication that also tells you what records it expects.
| Item | Schedule C line | The rule from Publication 463 | 2026 figure |
|---|---|---|---|
| Driving to shoots, meetings, the post office for merch | Line 9 (car and truck) | Standard mileage or actual costs; for a car you own, standard mileage must be chosen in the first year it is used for business or it is off the table later; commuting to a fixed workplace is not deductible | 72.5 cents per business mile, effective January 1, 2026 |
| Flights, hotels, rideshares for a trip that is primarily business | Line 24a (travel) | Personal days and companion costs come out; a vacation with a vlog in it is still a vacation | — |
| Meals with a sponsor, collaborator, or while traveling for business | Line 24b | Generally 50% of the unreimbursed cost | — |
| Concert tickets, a game, a club night with a brand rep | Nowhere | Entertainment expenses are generally nondeductible; the meal bought separately at the event can still be 50% | — |
| Records for all of the above | — | Adequate records, timely kept: date, place, amount, business purpose, and who was there | — |
Two of the ten guides on this query still list event tickets and movie tickets as deductible. That stopped being true with the 2018 tax-law change; Publication 463 is explicit that entertainment events and facilities do not qualify. If the ticket and the dinner are on one receipt, ask for them separately.
The first-year mileage rule matters more than the rate. Claim actual expenses on a car in year one and standard mileage is gone for that car; claim standard mileage in year one and you can move between methods later. For a creator who drives a normal car a few thousand business miles a year, standard mileage plus a log app is the right call.
Ads, giveaways, gifts: the $25 line
Money spent to bring viewers in is advertising on line 8: paid promotion, a thumbnail designer, a landing page, promotional stickers. A giveaway open to the audience is advertising too, because the purpose is reach.
A present to one person is different. Publication 463 caps business gifts at $25 per recipient per year. A $200 bottle to a brand contact yields a $25 deduction; a $200 prize drawn from your subscribers is a $200 advertising expense. Same money, different line, different result, and the difference is who could receive it.
People you pay
An editor, a thumbnail artist, a virtual assistant, or a second camera operator paid as a contractor goes on line 11, contract labor. The moment you pay one of them, you inherit a payer’s obligation: for payments made after 2025, the 1099-NEC threshold is $2,000 per contractor per year, and the statement has to reach them and the IRS by January 31. Collect a W-9 before the first payment, not in January.
A lawyer for a sponsorship contract, an accountant for the business return, or a bookkeeper goes on line 17, legal and professional services. Only the business share of a tax-prep bill belongs there; the part that prepares the rest of your Form 1040 is personal.
Courses, clothes, props, merch
| Item | Schedule C line | Governing source | The rule that bites |
|---|---|---|---|
| A course, workshop, or conference that improves skills you already sell | Line 27a | Publication 970 | Education that maintains or improves skills in your present work qualifies; education that qualifies you for a new trade does not — an editing course for an editor is in, a coding bootcamp is out |
| Clothing and grooming | Line 22, and only rarely | Publication 529 | Deductible only when not suitable for everyday wear — theatrical clothing and accessories; the jacket you could wear to dinner fails, however many videos it was in |
| Props, backdrops, consumables used on set (ingredients for a recipe video, materials for a build) | Line 22 (supplies) | Publication 334 | Business-use share; groceries the family also eats are not supplies |
| Merch you sell | Part III, cost of goods sold, flowing to line 4 | Schedule C instructions | Inventory is recovered as it sells, not when you buy it; unsold hoodies are not a deduction yet |
The clothing rule is the one creators want to be different. It is not. Publication 529’s wording covers musicians and entertainers and their theatrical clothing that cannot pass as street wear. A cosplay build, a character wardrobe, or a costume for a sketch channel fits that; a haul of ordinary clothes does not, whatever the caption said.
Bought the gear before the channel made money?
Most guides start the clock at the first payout. The tax code starts it at the first dollar of revenue, and everything before that is a start-up cost, not a current expense. Publication 583 and the Schedule C instructions let you elect to deduct up to $5,000 of start-up costs in the first year the business is active. The $5,000 shrinks dollar for dollar once total start-up costs pass $50,000, and whatever is left is amortized rather than lost.
For a creator that means the camera, the lights, and the editing software bought eight months before monetization are not simply “last year’s problem.” Total them, keep the receipts, put the election on the first return with income. If the total is under $5,000, the whole thing lands in year one. If it is over, the rest comes back over 180 months, which is small money each year but not zero.
Deductions that are not on Schedule C
This is the table the other guides skip, and it changes what you expect to owe. Four common “creator write-offs” never touch Schedule C. They live on Schedule 1 or on their own form, which means they reduce income tax but leave net profit — and therefore the 15.3% self-employment tax — exactly where it was.
| Deduction | Where it actually goes | Source | Effect on self-employment tax |
|---|---|---|---|
| Deductible half of self-employment tax | Schedule 1, line 15 | Form 1040 instructions; IRS SE tax page: the deduction “only affects your income tax,” not net earnings or SE tax | None |
| SEP, SIMPLE, or solo 401(k) contributions | Schedule 1, line 16 | Form 1040 instructions | None |
| Self-employed health insurance premiums (you, spouse, dependents) | Schedule 1, line 17, via its worksheet | Form 1040 instructions | None |
| Qualified business income deduction, up to 20% of QBI | Form 8995 or 8995-A, on the 1040 | IRS QBI page; made permanent by the 2025 law | None |
Why it matters, with invented numbers: a creator with $40,000 of profit who adds $6,000 of health premiums and a $4,000 SEP contribution has cut taxable income by $10,000 but still pays self-employment tax on the full $40,000. The only way to reduce that 15.3% is to reduce Schedule C profit, which is the whole reason the line-by-line map above exists. The math, with the 2026 rates and a worked example, is in quarterly estimated taxes for creators.
The records the IRS asks for, and the day to make them
Publication 583 lists what counts as proof: for expenses, canceled checks, account statements, credit card slips, invoices or receipts; for assets, the purchase invoice and the placed-in-service date. The general retention rule is three years from filing, stretching to six if income was under-reported by more than 25% and to the disposal year plus the limitations period for anything you depreciated. Car and travel expenses carry the stricter “timely kept” standard from Publication 463: a log written at the time, not rebuilt in March.
The day that matters is the day of the purchase, and this is where an operating habit beats any app. I have collected AdSense payouts for years, and the rule I run on them is to book each one as gross the day it lands — not mine yet, tax still inside it. The purchase side gets the same reflex: the day a card is charged for anything the channel touches, it gets a tag — business, personal, or split with a percentage — and a one-line note of which video or product it served. Ninety seconds then saves an afternoon of guessing later, and the guessing is what fails an audit.
The tag-day checklist, in order:
- Was it paid from the business account? If not, move the reimbursement now and note it.
- Which Schedule C line does it belong to? If you cannot name one from the tables above, it is personal or a question for a professional.
- Is it shared with personal life? Write the percentage and how you got it.
- Is it a single item or invoice over $2,500? Flag it for Form 4562 and the placed-in-service date.
- Is it a car, travel, meal, or gift? Add date, place, purpose plus who was there, today.
- Is it a contractor? Confirm the W-9 is on file and running total against $2,000.
- Save the receipt where next April’s you can find it, and keep it three years after that return is filed.
This week’s move: open last month’s card statement, put a Schedule C line number beside every business row using the tables above, and make a short list of the rows you could not place. That list is the only thing to bring to a tax professional — the rest is already done.
Frequently asked questions
Can I deduct a camera under $2,500 in the year I buy it?
Usually, yes. The IRS de minimis safe harbor lets a taxpayer without audited financial statements expense items costing up to $2,500 per invoice or item, provided a short election statement titled after Regulation 1.263(a)-1(f) is attached to a timely filed return. No depreciation schedule is needed. Above $2,500, Section 179 or bonus depreciation in Publication 946 applies.
Can I claim a home office if I film in my bedroom?
Only for a part of the room used exclusively and regularly for the business. A corner with a permanent camera rig and nothing personal in it can qualify; the whole bedroom cannot, because sleeping there is personal use. Measure the exclusive area, and if you use the simplified method the deduction is $5 per square foot with a 300-square-foot ceiling.
If a brand sends me a free product, can I deduct it?
It is income first. The IRS gig economy page says income must be reported whether it is paid in cash, property, goods, or virtual currency, so a product received for a review is revenue at its value. If the channel then uses it as gear, the business-use share can be recovered like any purchase. If it goes on a shelf at home, there is nothing to deduct.
Are clothes and makeup deductible for creators?
Rarely. Publication 529 allows entertainers to deduct theatrical clothing and accessories that are not suitable for everyday wear; a jacket you could wear to dinner fails that test even if it appeared in ten videos. Costumes, character wardrobe, and props used only on set are the defensible cases. Routine grooming is personal.
Do health insurance premiums reduce my self-employment tax?
No. The self-employed health insurance deduction goes on Schedule 1, line 17, not Schedule C, so it lowers income tax but leaves net earnings from self-employment and the 15.3% tax unchanged. The same is true of retirement contributions on line 16 and the deductible half of self-employment tax on line 15.
Sources
- IRS: Instructions for Schedule C (Form 1040) (2025)
- IRS: Tangible property final regulations (de minimis safe harbor election)
- IRS Publication 946 (2025): How To Depreciate Property
- IRS Publication 463 (2025): Travel, Gift, and Car Expenses
- IRS: IRS sets 2026 business standard mileage rate at 72.5 cents per mile
- IRS Publication 587 (2025): Business Use of Your Home
- IRS Publication 334 (2025): Tax Guide for Small Business
- IRS Publication 583: Starting a Business and Keeping Records
- IRS: How long should I keep records?
- IRS Tax Tip: Hobby or business? Here's what to know about that side hustle
- IRS Publication 529: Miscellaneous Deductions
- IRS: Instructions for Forms 1099-MISC and 1099-NEC
- IRS: Self-employment tax (Social Security and Medicare taxes)
- IRS: Instructions for Form 1040 and Schedule 1 (2025)
- IRS: Qualified business income deduction
- IRS: The One, Big, Beautiful Bill — what gig economy workers should know
- IRS: Gig economy tax center
- IRS Publication 970: Tax Benefits for Education (work-related education)
This article is general information based on the author's experience. It is not licensed financial, legal, or tax advice. See the editorial policy.